FIND YOUR Dream Home
 Back to Blog postings
Sarasota Real Estate Market: Inventory Drops as Waterfront Luxury Sales Lead August 2026
Sarasota Real Estate Market Report – August 2026
The Sarasota real estate market showed several encouraging signs in August, led by lower inventory, faster sales, and continued strength in the luxury and waterfront segments.
While prices were relatively stable compared with last year, buyers had fewer properties to choose from than they did in August 2025. At the same time, homes that sold moved to contract considerably faster.
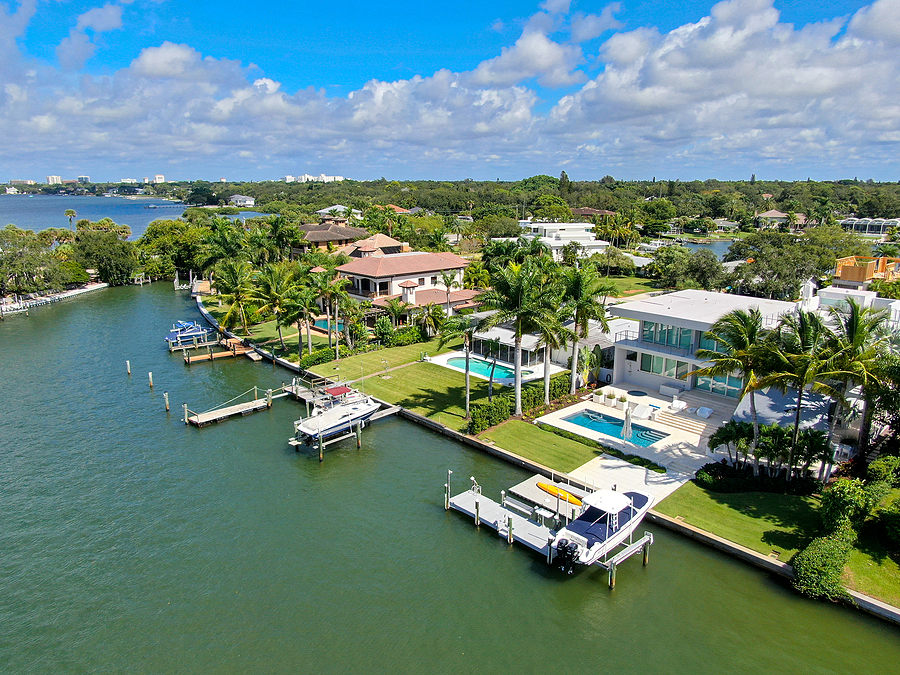
And at the top of the market, Sarasota’s waterfront lifestyle continued to command attention: 8 of the 10 highest-priced sales in the coastal region were waterfront properties, including the month’s top sale—a Bird Key waterfront estate that closed for $10.5 million.
Sarasota Luxury Real Estate Remains Active
Luxury real estate continued to account for a significant portion of Sarasota County’s August activity.
The month saw 78 single-family sales of $1 million or more. That included:
- 23 sales from $1 million to $1.249 million
- 13 sales from $1.25 million to $1.499 million
- 19 sales from $1.5 million to $1.999 million
- 13 sales from $2 million to $2.999 million
- 7 sales from $3 million to $4.999 million
- 2 sales from $5 million to $9.999 million
- 1 sale of $10 million or more
Waterfront Real Estate Dominates Sarasota’s Top Sales
The luxury market tells an even more interesting story when you look specifically at Sarasota’s highest-priced properties.
Eighty percent of the 10 sales in the coastal region during August were waterfront properties.
That concentration reinforces the premium buyers continue to place on Sarasota’s coastal lifestyle. Bird Key, Longboat Key, Lido Key, Siesta Key and Sarasota’s other waterfront neighborhoods offer something that cannot simply be replicated. Direct access to Sarasota Bay and the Gulf, boating, water views, and proximity to the area’s beaches and cultural amenities are hard to beat!
Scarcity also matters. Premier waterfront property is finite, especially homes with desirable water frontage, views, and boating access.
For luxury buyers, that means evaluating more than price per square foot. Water depth, bridge restrictions, dockage, seawall condition, boating access, view orientation, lot position, and proximity to the Gulf can create substantial value differences between properties that may initially appear comparable.
New Construction Continues to Drive Golf Community Sales
New construction remains another important part of the Sarasota-area real estate market, particularly for buyers looking for golf and resort-style communities.
Some of the region’s most active new-home development is occurring in and around Lakewood Ranch and Wellen Park, which continue to rank among the country’s top-selling master-planned communities. Through the first half of 2026, Lakewood Ranch recorded 1,064 new-home contracts while Wellen Park recorded 727, up 37% from the same period last year.
Golf communities are contributing to that activity as well.
In Wellen Park Golf & Country Club, new construction has accounted for a significant share of recent closings as Lennar continues building out the bundled golf community. An analysis of recorded sales through the first half of the year found that approximately 65% of sales during the preceding 12 months were new construction.
New construction is also an important part of the golf market farther north in the Lakewood Ranch area, including communities such as Esplanade at Azario, where buyers continue to have both new-build and quick-move-in opportunities. Current offerings span a wide range of home sizes and price points.
For golf buyers, however, comparing new construction with resale requires looking beyond the home price.
Builder incentives, closing-cost contributions, and financing incentives can affect the true cost of a new home. Just as important are the golf membership structure, initiation or capital fees, annual dues, membership availability, and the timing of future amenities.
A resale home may offer upgrades, an established neighborhood, and immediate access to club amenities, while new construction gives buyers the opportunity to select a newer home and, in some cases, take advantage of builder incentives.
That is why we help our clients compare new construction and resale side by side. The goal isn’t simply to determine which house costs less. It’s to determine which home, golf membership, and community best fit how they plan to live.
Sarasota Single-Family Home Sales
Sarasota County recorded 646 single-family home sales in August, nearly the same as the 641 sales recorded a year earlier. The median sales price was $470,000, down just 1.1% from $475,000 in August 2025. The average sales price was $670,413.
The bigger change is in inventory.
Active single-family inventory fell to 2,619 homes, a 20.8% decline from last year. Months of supply dropped from 5.2 months in August 2025 to 3.7 months in August 2026, a 28.8% year-over-year decline.
That is a meaningful shift. Buyers still have choices, but sellers face considerably less competition from other listings than a year ago.
|
Closed Sales
646
▲ +0.8% YoY
|
Median Sale Price
$470,000
▼ -1.1% YoY
|
Average Sale Price
$670,413
▼ -1.9% YoY
|
Dollar Volume
$433.1M
▼ -1.2% YoY
|
|
Pending Sales
665
▲ +1.1% YoY
|
New Listings
762
▲ +3.5% YoY
|
Inventory
2,619 Homes
▼ -20.8% YoY
|
Months Supply
3.7 Months
▼ -28.8% YoY
|
|
Cash Sales
241
▲ +3.4% YoY
|
Median Time to Contract
47 Days
▼ -31.9% YoY
|
Median Time to Sale
91 Days
▼ -16.5% YoY
|
Key Takeaway Homes Are Moving Faster
One of this month’s more interesting statistics is time to contract.
The median single-family home that sold in August went under contract in 47 days, compared with 69 days last August—a 31.9% decrease. Median time from listing to closing also declined from 109 days to 91 days.
Sellers also received a median 94.7% of their original asking price, up from 92.3% a year ago.
Taken together with declining inventory, the numbers suggest a market that is becoming more competitive for well-positioned properties even though the median price remains relatively flat.
Sarasota Condo and Townhome Market
The condominium and townhome market also improved in several important areas.
Condo and townhome sales totaled 281 in August, up 13.8% from 247 a year ago. The median sales price increased 3.3% to $310,000, while dollar volume jumped 19.1% to $124.1 million.
Inventory also moved sharply lower.
There were 1,659 active condo and townhome listings, down 11.8% year over year. Months of inventory declined from 7.0 months to 5.2 months, a 25.7% decrease.
|
Closed Sales
281
▲ +13.8% YoY
|
Median Sale Price
$310,000
▲ +3.3% YoY
|
Average Sale Price
$441,558
▲ +4.7% YoY
|
Dollar Volume
$124.1M
▲ +19.1% YoY
|
|
Pending Sales
298
▲ +14.2% YoY
|
New Listings
341
▲ +1.8% YoY
|
Inventory
1,659 Condos
▼ -11.8% YoY
|
Months Supply
5.2 Months
▼ -25.7% YoY
|
|
Cash Sales
168
▲ +9.8% YoY
|
Median Time to Contract
83 Days
▼ -4.6% YoY
|
Median Time to Sale
124 Days
▼ -6.1% YoY
|
Key Takeaway
The condo numbers are particularly noteworthy because sales increased while inventory decreased. New pending sales were also up 14.2%, suggesting buyers remained active heading into the fall market.
What Does the August Sarasota Market Mean for Buyers?

The Sarasota market still offers buyers negotiating opportunities, but the data doesn’t support treating every property as though sellers are under pressure to unload their homes.
Inventory is moving in the opposite direction.
Single-family inventory is down more than 20% from last year, while condo inventory is down nearly 12%. Single-family homes that ultimately sold were also going under contract substantially faster.
For buyers focused on waterfront properties, golf communities, or other highly desirable neighborhoods, broader Sarasota County statistics tell only part of the story. Inventory and negotiating leverage can vary dramatically from one neighborhood—or even one street—to another.
A property with the right location, view, golf membership, boating access, or waterfront exposure may face very different supply-and-demand conditions than the countywide market.
What Does the Market Mean for Sarasota Sellers?
For sellers, declining inventory means less competition than a year ago.
That does not mean buyers will overlook an unrealistic asking price. But properly positioned homes can stand out, especially as Sarasota heads into its traditionally active winter and spring selling season.
The improvement in the median percentage of original list price received and the sharp decline in time to contract for single-family homes are both worth watching as we move through the remainder of 2026.
Sarasota Real Estate Outlook

August’s numbers point to a tightening Sarasota market, not a broad increase in available homes.
Single-family inventory fell 20.8%. Condo inventory fell 11.8%. Single-family homes sold faster. Condo sales increased 13.8%. And eight of the coastal region’s 10 highest-priced sales were waterfront properties.
For buyers, the opportunity is still there—but the best strategy depends heavily on the specific community, neighborhood, and property type.
For sellers, understanding what’s happening in your segment of the market is equally important. Countywide statistics provide useful context, but the value of a waterfront estate on Bird Key, a home in a private golf community, a downtown Sarasota condo and a property east of I-75 will be driven by very different competitive sets.
Thinking about buying or selling in Sarasota, Lakewood Ranch, Venice or one of Southwest Florida’s golf communities? Our team can help you evaluate the market at the community and neighborhood level, identify relevant comparable sales, and understand how the property’s location, amenities, golf privileges, or waterfront characteristics affect its value.
📲 Call or Text: 239-370-0892
🌐 Search Homes: NaplesGolfGuy.com
Sarasota Real Estate Market August 2026 – Single Family Homes
About Naples Golf Guy
For expert guidance in Southwest Florida real estate, contact Naples Golf Guy, Matt Klinowski P.A. Whether you’re looking to buy a single-family home or condo in Naples, Bonita Springs, Estero, Ft. Myers or Sarasota I can help. With over 20 years of experience, I offer valuable market information and insights into individual communities to help you find the perfect home and lifestyle in the best golf community to fit your needs. Reach out to me today to get started!
Contact Matt: [email protected] or at 239-370-0892